
Chinese cars account for 10% of Western Europe's new car market during 2026


According to Schmidt Automotive Research data, Chinese manufacturers accounted for more than 10% of the Western European new passenger car market cumulatively, with 820,000 units registered in the first two-thirds of 2026.
However, the first signs of a slower growth pace emerged, with market share rising by just 0.5 ppts over the last four months between May and August, compared with 1.4 ppts during the opening four months of the year, from January to April.
August nonetheless saw Chinese models collectively account for a record 11.5% of the regional new car market.
BYD, which is now half a percentage point away from equalling Ford’s regional market share, which has sunk dangerously close to 3%, is now the region's leading Chinese brand, having edged ahead of SAIC's MG brand this year, with BYD achieving 2.6% market share so far this year compared to MG’s 2.5%, followed by Chery's collective brands equalling 2.3%.
Consequently, those three manufacturers form what we call the C3, accounting for three in four of all the Chinese-brand models delivered across the region this year.
Stellantis's Leapmotor is the next-largest Chinese brand, just missing 1% market share this year. However, that is only a matter of time given the expanded product portfolio, with the B03 and B03X models arriving imminently and the fact that two local Stellantis production facilities will soon begin manufacturing models in Europe, avoiding punitive tariffs placed on Chinese-made BEVs since November 2024 as well as a standard 10% import tariff to the region.
However, the brand also benefited from special effects across Italy early in the year, with Chinese models qualifying for Italian purchase subsidies during 2025 and delivery lags boosting the T03 model there, leading to every fifth regional Leapmotor ending up in Italy this year. That positive effect is expected to weaken in the closing part of the year, however.
From a more premium perspective, Xpeng is edging closer to Polestar, with fewer than 1,000 units now separating them after 8 months this year.
The Xpeng L03 rollout will help from the closing months of 2026, benchmarking on both price and technology against the region's number one electric car, the Tesla Model Y.
Polestar is suffering from Geely cannibalisation as Zeekr models roll out more widely across the region. It will also suffer from Volvo Cars (we don't qualify Volvo as Chinese), EX60 rollout in the closing 4 months of the year.
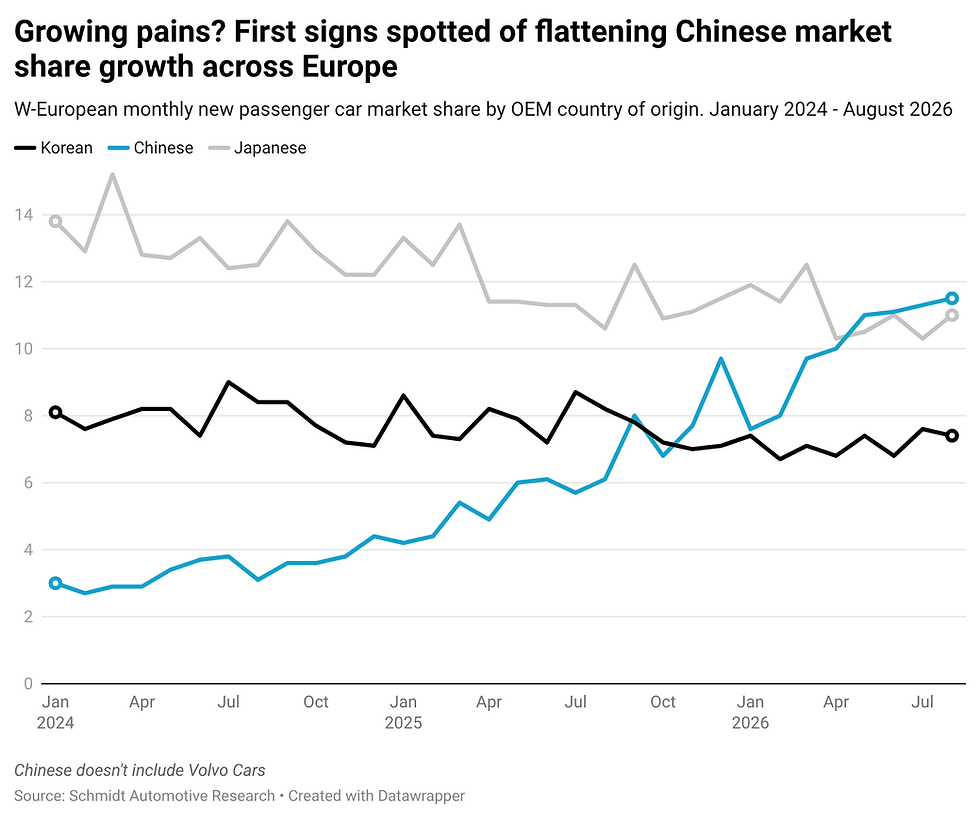
Chinese models are set to receive a positive, seasonality-driven boost in September due to the UK's registration plate changeover and the regional Chinese weighting there, which sees just under 30% of all regional Chinese models end up there, according to our own exclusive research and data.
However, the pace is then expected to slow further during the final quarter, despite a front-loading of non-BEVs spotted as Chinese manufacturers rush models to market before a potential widening of the EU anti-tariff scope, likely sometime during 2027, as incumbent European OEMs in particular, such as Volkswagen Group and German premium brands, benefit from positive product cadence effects with more competitive and compelling models entering the market.
This is just a small extract from one of our full studies which are available below.
To discover more about out studies just contact us
Scope: Western Europe's 18 Markets: EU Member States prior to the 2004 enlargement, plus EFTA markets Norway, Switzerland, Iceland, plus UK – accounting for 90% of the enlarged European region.


Comments